
Protecting Your Business Property
A fire, flood, water damage, storm or another unexpected event can cause significant material damage in a very short period of time and seriously affect the continued operation of a business.
Property insurance can protect different types of business property and can be tailored to the company’s activities, locations, property values and the risks to which it is exposed.
The purpose of appropriately structured insurance is not only to compensate for the damage incurred, but also to enable the business to resume normal operations as quickly as possible.
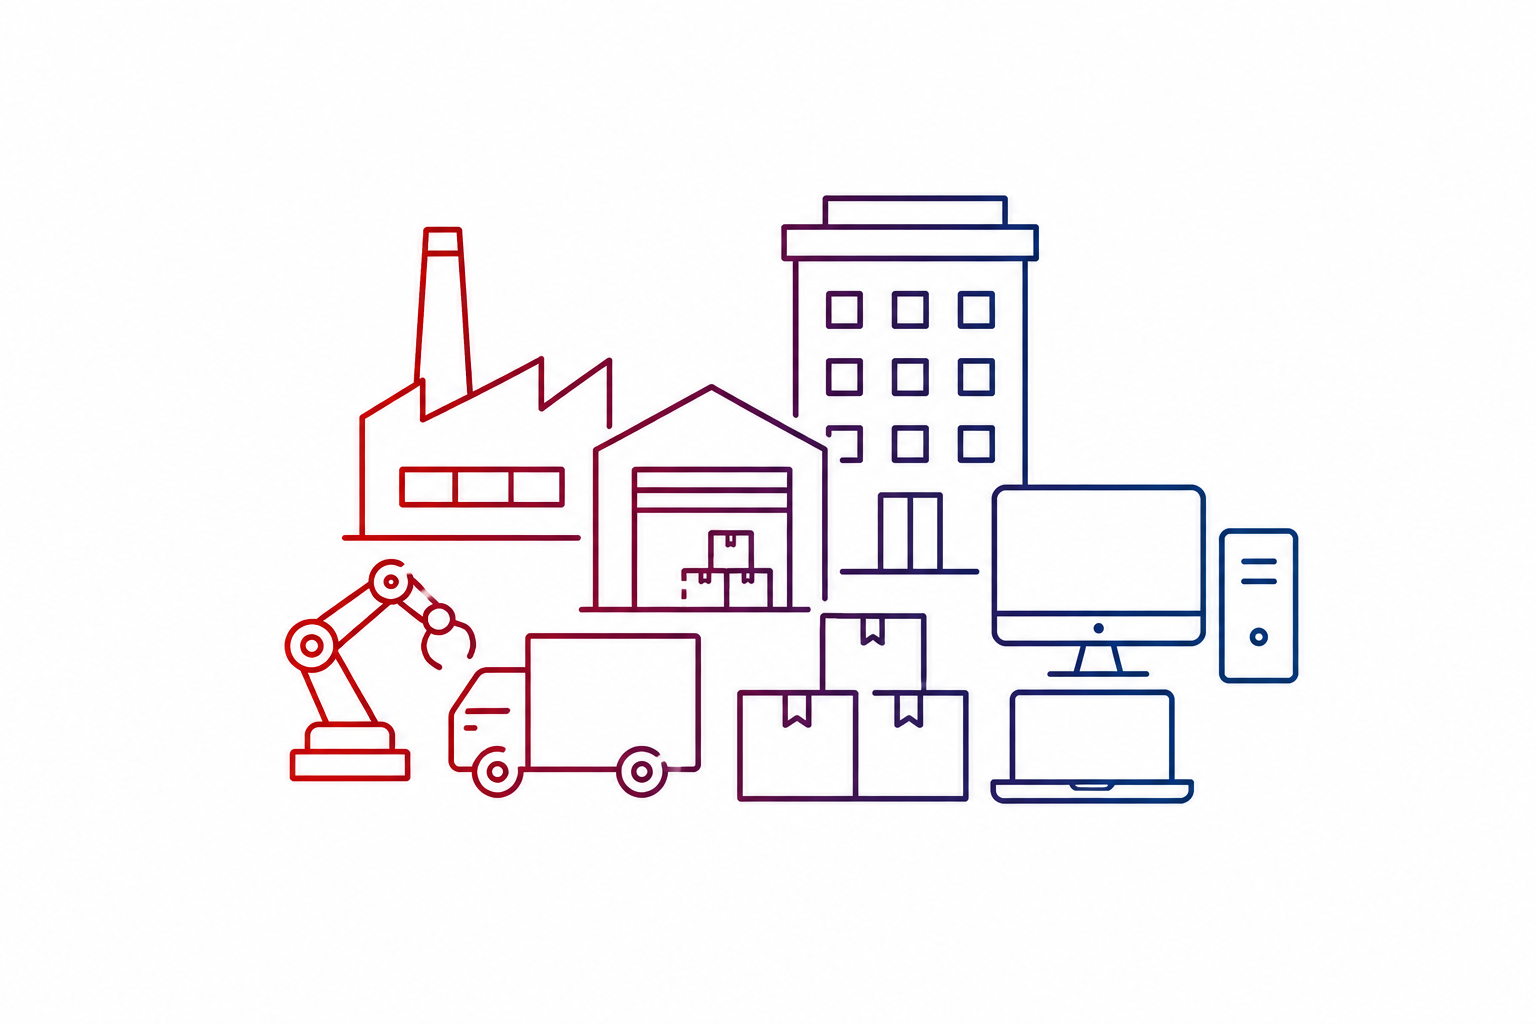
What Can Be Insured?
The property to be insured depends on the activities and structure of each individual business. Insurance may include, among other things:
Insured values and the scope of cover are determined according to the actual property and the individual needs of the business.
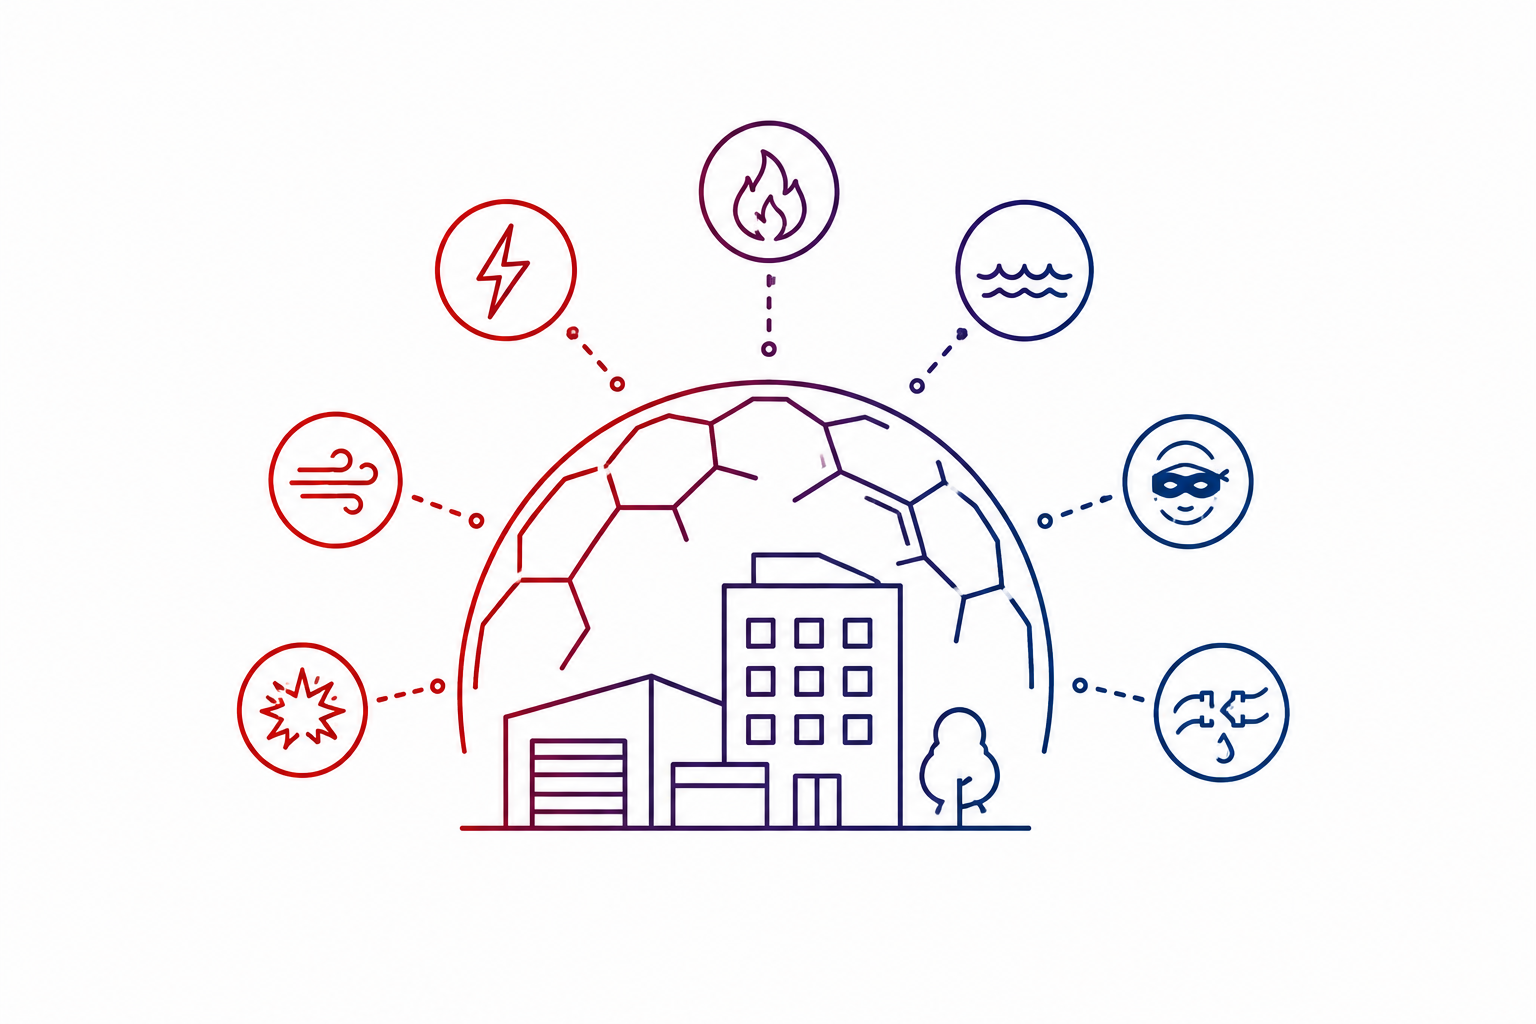
What Risks Can Your Property Be Protected Against?
Property insurance can cover damage caused by a range of risks. Depending on the selected insurance solution, cover may include:
The scope of cover is not the same under every policy. It is therefore important to consider not only which risks are covered, but also the applicable limits, exclusions, sums insured and deductibles.
Fire and Other Basic Perils
Fire is one of the traditional, yet still significant, risks to business property. Damage caused by fire is not necessarily limited to the building itself. Machinery, equipment, stock, raw materials and other assets required for business operations may also be affected.
In addition to direct physical damage, a fire may result in clean-up and debris removal costs as well as an extended interruption to business operations.
When assessing the risk, factors such as the construction of the building, business activities, fire load, fire detection and suppression systems and other preventive measures are therefore also important.
Machinery Breakdown and Electronic Equipment
For businesses whose operations depend on machinery, production lines or other technical equipment, cover for traditional fire perils alone is often not sufficient.
Machinery breakdown insurance can provide protection against sudden and unforeseen damage to machinery and equipment, while appropriate additional cover can be arranged for computer, communication and other electronic equipment.
The scope of insurance is tailored to the type of equipment, its value and age, as well as its importance to the business process.
When Property Damage Also Interrupts Your Business
Physical damage may be only the first part of the financial consequences of an insured event. If a fire or another insured peril prevents a business from continuing production or providing its services, it may also result in a significant loss of revenue.
Business Interruption insurance can help protect a business against the financial consequences of such an interruption.
Depending on the agreed terms, cover may include loss of gross profit or revenue, fixed costs that the business must continue to pay during the interruption, and certain additional costs incurred to resume operations as quickly as possible.
It is also important to establish an appropriate maximum indemnity period, as recovery from a major loss and the restoration of normal business operations may take several months.
Appropriate Insured Values Are Essential
Even broad insurance cover may not provide adequate protection if insured values are set too low.
When arranging insurance, it is therefore important to properly assess the value of buildings, machinery, equipment, stock and other property and to review how the sums insured are determined.
This helps reduce the risk of underinsurance, which may result in an insurance payment being lower than the actual amount of the loss.

Local Support and Access to the European Market
Property insurance can be arranged on the Slovenian insurance market, where we identify an appropriate combination of cover and terms for each individual risk.
For larger or more complex risks, higher property values, specialised business activities or companies operating from locations in several countries, we can also explore solutions available across the wider European insurance market.
This can provide access to a broader range of solutions, additional insurance capacity and support in structuring insurance programmes for more complex property risks.

A Solution Tailored to Your Business
Every business has different property and a different risk profile. When arranging insurance, we therefore analyse the company’s activities, locations, the value of buildings and equipment, production processes, stock, fire protection and other preventive measures, as well as the potential consequences of a business interruption.
Based on this analysis, we identify an insurance solution that reflects the company’s actual exposure and provides an appropriate balance between the scope of cover, sums insured and the cost of insurance.
Protect the property your business depends on.